
MOT tester
invoice template
Tests carried out for testing stations, invoiced per test or per day.
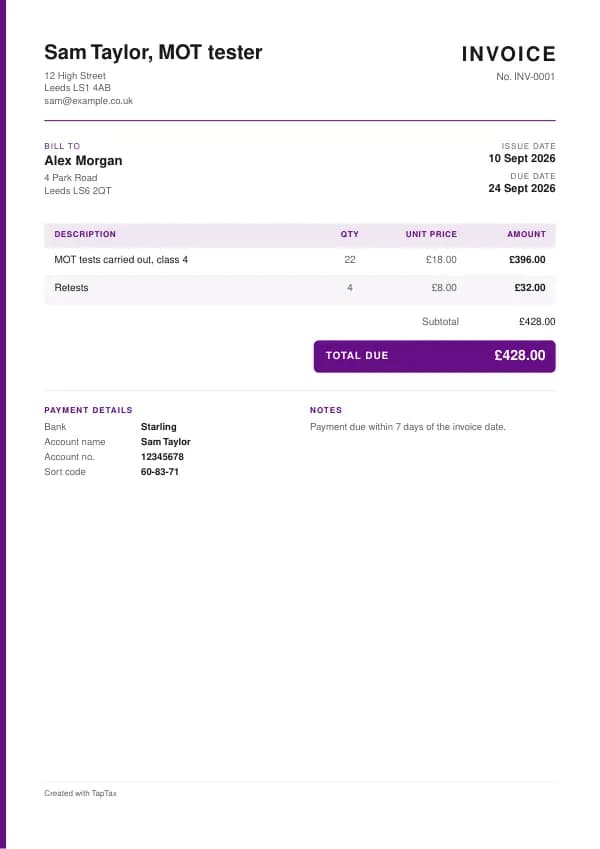
Download the MOT tester invoice template
Free, with no sign-up. Replace the words in square brackets with your own details; the example lines are ready to keep or change.
Opens the free invoice generator with these lines in place. Make a PDF in your own colours, with your logo. Nothing is stored.
Self-employed MOT testers invoice garages and testing stations for carrying out tests on their premises, usually per test or per day. This free template sets out a MOT tester invoice the way customers expect to see it, with example lines you can keep or replace.
What goes on a MOT tester invoice
List the dates, the number of tests or hours, the testing station, and any retests. Keep the test records from the MOT system to support the numbers.
| Line | Quantity | Price | Amount |
|---|---|---|---|
| MOT tests carried out, class 4 | 22 | £18.00 | £396.00 |
| Retests | 4 | £8.00 | £32.00 |
| Subtotal | £428.00 | ||
| Total due | £428.00 |
Line by line: MOT tests carried out, class 4, 22 × £18.00 = £396.00; Retests, 4 × £8.00 = £32.00. The subtotal is £428.00. The example assumes you are not VAT registered, so there is no VAT and the total due is £428.00. The figures are illustrative, not a price guide, so use your own rates.
Whatever the job, a UK invoice must carry the basics GOV.UK lists: a unique invoice number, your name or business name and an address, your customer's name and address, a clear description of what you are charging for, the date the work was done and the date of the invoice, the amounts, any VAT, and the total owed. The template has a place for each, and the guide to what a UK invoice must include explains the rules behind them.
Number invoices in one unbroken sequence, such as INV-0001, INV-0002 and so on, and never reuse a number, even for a cancelled invoice. The invoice number generator suggests a format and works out your next number.
How MOT testers price their work
Testers are paid per test or by the day by the testing station. The station, not the tester, charges the motorist, and the statutory maximum fee for a car MOT is £54.85.
Whatever the model, write it on the invoice as the customer agreed it: the unit (hour, day, job, item), the quantity and the rate on each line. A customer who can see how a total was built pays faster than one who has to ask. If you are working out what to charge in the first place, the day rate calculator works back from the income you want, and the markup calculator shows what you keep on anything you buy in.
Agree this before you start
Agree the rate per test or per day, retest payments, who holds the testing station authorisation, and how quality control and disciplinary points are handled.
When to send a MOT tester invoice
Weekly or monthly, with the count of tests.
The sooner an invoice goes out, the sooner it is paid: the payment clock starts when the customer receives it. Send it by email as a PDF on the day the work is finished, and the guide to sending an invoice covers what to put in the email.
VAT on MOT tester invoices
An approved test centre may treat the MOT fee it charges the motorist as outside the scope of VAT, as long as it does not exceed the statutory maximum (VAT Notice 700, section 25.4), but a self-employed tester's charge to the garage for carrying out tests is an ordinary business service, standard-rated if the tester is VAT registered.
Transport and motor services are standard-rated at 20% once you are VAT registered. Two exceptions come up: passenger transport in a vehicle designed or adapted to carry 10 or more passengers is zero-rated, and second-hand vehicles can be sold under the margin scheme, which charges VAT only on your profit. Until turnover reaches £90,000 you need not register, and an unregistered business shows no VAT.
You must register for VAT when your taxable turnover over any rolling 12 months goes above £90,000, or you expect it to in the next 30 days alone. The VAT registration checker tracks where you are, and invoicing without a VAT number explains what an unregistered invoice looks like.
Who MOT testers invoice
Business customers, including logistics firms, agencies and garages, often pay only against an invoice that quotes their job or purchase order number, and many run fixed payment runs. Ask for their invoicing instructions before the first job. Where an agency places you, check whether they self-bill (issue the invoice on your behalf) so you do not invoice twice.
Working for one station on its premises, on its equipment and its hours, can look like employment; testers who work across several stations and invoice each one have the clearest self-employed position.
Recharging costs and expenses
Costs you pay out for a job, such as travel, parking, materials or specialist hire, can be passed on to the customer when you agreed to it. Put each on its own line with a short description, and keep the receipts. Recharged costs are part of your income, and the original cost is your expense; if you are VAT registered, VAT is normally charged on the recharge at the rate of your main service. Only a genuine disbursement, a cost paid purely as the customer's agent, is passed on without VAT. The mileage calculator shows what business travel is worth at HMRC's rates.
Mileage, waiting time and fuel
Distance and time are what transport customers pay for, so show them. Put the collection and delivery points on each job line, the miles or the agreed zone, and any waiting time at the rate you quoted. If your rate includes fuel, say so; if you add a fuel surcharge when prices move, agree it in writing first. For your own tax, keep a mileage log for the vehicle whatever method you use: under HMRC's simplified expenses, cars and vans can claim 45p a mile for the first 10,000 business miles and 25p after that, instead of actual running costs, but you must choose one method per vehicle and stick with it. The mileage calculator shows what your miles are worth.
Deposits, stages and cancellations
Not applicable.
Deposits suit bookings that block out a day or tie up a vehicle, such as a house move or a long-distance job. Charge waiting time and extra drops at the rates you quoted, and show them as their own lines so the customer can see why the total moved.
Payment terms for MOT testers
Stations commonly pay weekly or monthly.
If you agree no terms with a business customer, the law sets payment at 30 days after they receive the invoice or the work, whichever is later. Agreed terms between businesses can run to 60 days, or longer only where that is fair to both sides. When a business pays late, the Late Payment of Commercial Debts (Interest) Act 1998 lets you claim interest at 8% a year above the Bank of England base rate plus fixed compensation, which the late payment interest calculator works out. These rights do not apply to invoices sent to private individuals, so for household customers your own terms matter even more.
Fixed compensation for a late business payment
- Debt up to £999.99£40
- £1,000 to £9,999.99£70
- £10,000 or more£100
Getting paid faster
Three details decide how quickly most invoices are paid. First, your bank details on the invoice itself: account name, sort code and account number, with the invoice number as the payment reference so you can match the money when it lands. Second, a clear due date rather than "payment on receipt", which customers read as "whenever". Third, a polite reminder the day after the due date, then again at 7 and 14 days. A card payment link on the invoice helps with household customers, who are more likely to pay straight away if it takes one tap. The 30-day payment terms guide and invoice payment terms explain which terms to choose.
If a customer disputes the invoice
Most disputes are about scope: the customer thought something was included that you did not. Respond in writing, point to what was agreed, and separate the part in dispute from the rest, which should be paid on time. If only part of an invoice is questioned, a credit note for that part lets the undisputed amount be settled now. If a business customer still will not pay, a formal letter before action usually does it; after that, in England and Wales, the small claims track of the county court handles claims up to £10,000. The guides to invoice disputes and small claims for an unpaid invoice walk through each step.
Common MOT tester invoicing mistakes
- Counts that do not match the MOT system. The station will check your invoice against the testing service records; use those records as your source.
- Retests with no agreed rate. Agree whether retests are paid and at what rate before you start.
- Working for one station only. Testing for a single station, on its premises and its hours, can look like employment; working across stations supports self-employment.
- Showing VAT when you are not VAT registered. You can only charge VAT with a VAT number, and adding it anyway is an offence. If you are not registered, your invoice shows a total with no VAT line.
- Editing an invoice after sending it. Correct a mistake with a credit note and a new invoice, so your records and your customer's match. The guide to correcting an invoice shows how.
Checklist before you send it
Run through this before every invoice goes out. Each point is a reason invoices get paid late:
- The invoice number is the next in your sequence and has never been used.
- The customer's name and address are right, with their purchase order or reference if they use one.
- Each line shows what was done, the quantity, the unit and the rate.
- The subtotal and total add up, and VAT appears only if you are VAT registered.
- The invoice date, a due date and your bank details are on it.
- A copy is saved with your records before you press send.
Keep a copy of every invoice
You must keep your records for at least 5 years after the 31 January submission deadline of the relevant tax year.
Every invoice you issue is a record of income. Keep a copy of each one, digital is fine, along with the payments that settle them. From 6 April 2026, sole traders with qualifying income over £50,000 must keep digital records and send HMRC quarterly updates under Making Tax Digital, with the threshold falling to £30,000 from April 2027 and £20,000 from April 2028. The MTD requirement checker tells you when it applies to you, and how long to keep invoices covers the retention rules.
Download the MOT tester invoice template
The template comes in four forms. The Word version opens in Microsoft Word, Google Docs and Pages: replace the words in square brackets and save. The Excel version opens in Excel, Google Sheets and Numbers, and works as a calculator, so each line, the subtotal, the VAT and the total update as you type. The PDF is ready to print. Or skip the download and fill it in online with the free invoice generator, which opens with these MOT tester lines already in place and makes a PDF in your own colours, with your logo.
When a template stops being enough, a TapTax account, free to start, creates and sends your invoices, tracks which are paid, and files your quarterly updates to HMRC from the same records. Our guide for MOT testers covers the tax side: expenses, National Insurance and Making Tax Digital.
Tools for this
Related guides and definitions
Frequently asked questions
What should a MOT tester invoice include?
Your business name and address, a unique invoice number, the date, the customer's name, each piece of work with its price, the total, and your VAT number and the VAT if you are VAT registered.
Do MOT testers charge VAT?
Only if VAT registered, above £90,000 of turnover. Testing services to a garage are standard-rated.
When should a MOT tester send an invoice?
Weekly or monthly, with the number of tests.
Is this MOT tester invoice template free?
Yes. Download it in Word, Excel or PDF, or fill it in online with the free invoice generator. There is no sign-up, and nothing you type is stored.
Invoice, get paid, stay ready for HMRC.
TapTax creates and sends your invoices, tracks which ones are paid and files your quarterly updates to HMRC. Start on the free plan, no card needed.
Get started freeSources
The rules on this page come from official guidance.