
Reverse charge invoice
template
A construction VAT invoice under the domestic reverse charge, with the wording HMRC expects.
Download the reverse charge invoice template
Free, with no sign-up. Replace the words in square brackets with your own details.
Since March 2021, most construction services supplied between VAT-registered businesses in the CIS chain are invoiced under the domestic reverse charge. The subcontractor does not charge VAT; the contractor accounts for it on their own VAT return. The invoice still has to show the VAT that would have been charged, and a clear statement that the reverse charge applies. This template sets out the invoice and the wording.
- Reverse charge invoice
- A VAT invoice where the customer, not the supplier, accounts for the VAT to HMRC. In UK construction, the domestic reverse charge applies to most CIS work between VAT-registered businesses where the customer is not the end user.
When to use a reverse charge invoice
Use a reverse charge invoice when all of these apply: you are VAT registered; your customer is VAT registered and registered for CIS; the service is a construction service within CIS at the standard or reduced rate; and your customer is not an end user or intermediary supplier (a business that has told you it is using the work itself or selling it on unchanged to an end user). When any condition fails, such as work for a homeowner or a business improving its own premises, invoice VAT in the normal way.
What a reverse charge invoice must show
| What it shows | Why it matters |
|---|---|
| All the usual VAT invoice details | Number, tax point, both parties' details, your VAT number |
| Each service with its price excluding VAT and the VAT rate | The rate that would apply without the reverse charge |
| The amount of VAT due under the reverse charge | Shown on the invoice but not added to the total |
| A reverse charge statement | For example: "Reverse charge: customer to account to HMRC for the VAT" |
| A total that excludes the VAT | What the customer actually pays you |
| Labour and materials split, if CIS applies | So the contractor can apply the CIS deduction |
HMRC gives example wordings for the statement, including "Reverse charge: VAT Act 1994 Section 55A applies" and "Reverse charge: Customer to pay the VAT to HMRC". Any clear equivalent is fine.
An example reverse charge invoice
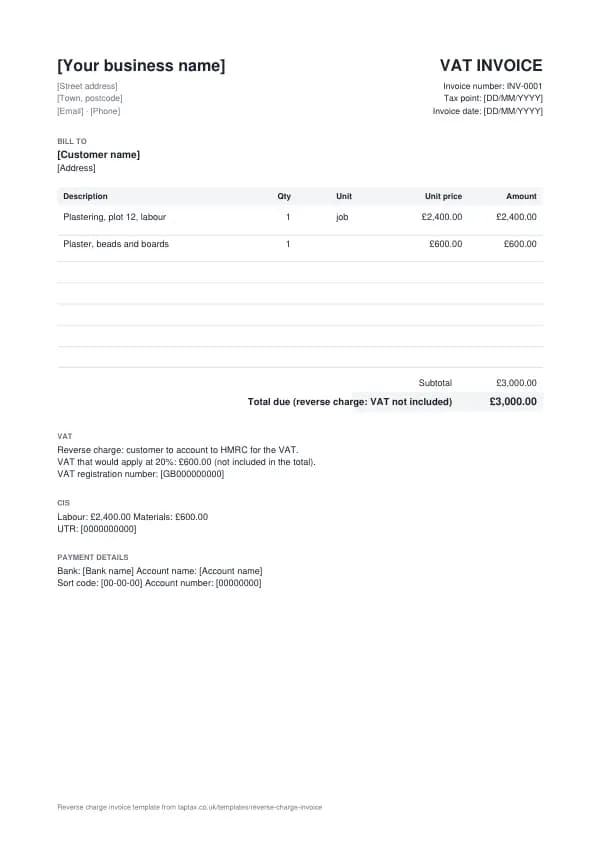
The template comes filled in with example lines like these, so you can see how each part works before replacing them with your own.
| Line | Quantity | Price | Amount |
|---|---|---|---|
| Plastering, plot 12, labour | 1 job | £2,400.00 | £2,400.00 |
| Plaster, beads and boards | 1 | £600.00 | £600.00 |
| Subtotal | £3,000.00 | ||
| Total due (reverse charge: VAT not included) | £3,000.00 |
Line by line: Plastering, plot 12, labour, 1 job × £2,400.00 = £2,400.00; Plaster, beads and boards, 1 × £600.00 = £600.00. The subtotal is £3,000.00, which is also the total due (reverse charge: vat not included) because no VAT is charged. The figures are illustrative; replace them with your own.
How to fill in the template
- Confirm the conditions: both of you are VAT registered, the customer is registered for CIS, the work is within CIS and the customer is not an end user.
- Fill in the usual VAT invoice details and list the services with prices excluding VAT.
- Split labour from materials if the customer will make a CIS deduction.
- Show the VAT rate and the amount of reverse charge VAT, but do not add it to the total.
- Add the reverse charge statement.
- Keep the customer's end user notification, or the evidence of their status, with your records.
Number every reverse charge invoice in sequence and never reuse a number, even when a document is cancelled. Numbers make documents easy to find and to match against payments, and they show HMRC and your customers that nothing is missing. For a numbering format, try the invoice number generator.
End users, intermediaries and the 5% rule
The reverse charge does not apply when your customer is an end user (a business receiving construction services for its own use, such as a retailer having its shop refitted) or an intermediary supplier connected to an end user, provided they tell you so in writing. It also does not apply to supplies at the zero rate, or where the customer is not registered for CIS. If the construction services within an invoice are no more than 5% of its value, the normal VAT rules can apply to the whole invoice. When in doubt, the reverse charge checker walks through each test.
CIS deduction rates
- Not registered for CIS30%
- Registered and verified20%
- Gross payment status0%
Reverse charge invoice or normal VAT invoice?
A normal VAT invoice adds VAT to the total and the supplier pays it to HMRC. A reverse charge invoice shows the VAT but leaves it out of the total, and the customer accounts for it. Using the wrong one means VAT is paid twice or not at all, and HMRC can correct both sides.
Cash flow for subcontractors
Under the reverse charge you no longer receive VAT from your customer, so you have less cash in hand between receiving payment and paying HMRC. Many subcontractors become repayment traders, because they still pay VAT on their materials but charge none on their sales. Monthly VAT returns can get repayments to you faster, and it is worth reviewing whether the Flat Rate Scheme still makes sense for you, as its benefit usually disappears under the reverse charge.
Reverse charge for services to overseas businesses
A different reverse charge applies to many services supplied to business customers outside the UK: the service is treated as supplied where the customer belongs, and the customer accounts for any VAT in their own country. Those invoices should show the customer's country and a note that the customer accounts for VAT, rather than UK VAT. That is not the construction domestic reverse charge, so do not use the construction wording for it.
Mixed contracts and materials
The reverse charge applies to the whole supply of construction services, including materials you supply as part of the work, when the conditions are met. Materials supplied on their own, without any installation, are outside it. Where a single contract mixes reverse charge and normal work, HMRC's guidance explains how to treat each part; the simplest approach is often separate invoices.
Checking your customer's status
Before invoicing under the reverse charge, check your customer's VAT number and ask whether they are an end user or intermediary. Many contractors now state their status in their subcontract or purchase order. Keep that confirmation with your records: if HMRC later decides the reverse charge should not have applied, having evidence of what you were told protects you.
Worked example
A plasterer who is VAT registered does £2,400 of labour and supplies £600 of materials on a new build for a main contractor that is VAT registered and registered for CIS. The invoice shows £3,000 of services, VAT at 20% of £600 shown as a reverse charge amount, and a total due of £3,000. The contractor deducts CIS at 20% from the labour only, £480, and pays £2,520, sending a payment and deduction statement. The contractor then records £600 as both output and input VAT on its own return, so the net effect for a fully taxable contractor is nil. The plasterer puts £3,000 in box 6 of their return and nothing in box 1 for this sale.
Common reverse charge invoice mistakes
- Adding VAT to the total. Show the VAT amount but do not include it; the customer pays you the net amount.
- Using the reverse charge for end users. Homeowners and businesses improving their own premises pay VAT normally.
- Leaving out the reverse charge statement. Without it the customer may not realise they must account for the VAT.
Checklist before you send it
A quick check of every reverse charge invoice before you send it:
- All the usual VAT invoice details is on it and correct.
- Each service with its price excluding VAT and the VAT rate is on it and correct.
- The amount of VAT due under the reverse charge is on it and correct.
- A reverse charge statement is on it and correct.
- A total that excludes the VAT is on it and correct.
- Labour and materials split, if CIS applies is on it and correct.
- A copy is saved with your records.
Sending it
Email the reverse charge invoice as a PDF with a short, specific message: the document number, the amount, and what you need the reader to do. Address it to whoever processes it, often an accounts team, and copy your usual contact if that helps. File the sent PDF with its number in the file name, so you can find it in seconds if there is ever a question.
Keep a copy
You must keep your records for at least 5 years after the 31 January submission deadline of the relevant tax year.
Business documents are records, and records have to be kept. Save every reverse charge invoice in one place, ideally digitally, so you can find it if a customer or HMRC asks. Making Tax Digital for Income Tax makes digital records compulsory from 6 April 2026 for qualifying income over £50,000, from April 2027 over £30,000 and from April 2028 over £20,000; check your date with the MTD requirement checker.
Download the reverse charge invoice template
Download it as a Word document, an Excel workbook or a PDF, whichever suits the way you work. The Word file opens in Google Docs too, and the Excel file in Google Sheets. The Excel totals are live formulas.
Related documents in the same family: the zero-rated invoice template, VAT-exempt invoice template, flat rate scheme invoice template, VAT invoice template and simplified VAT invoice template. All of them follow the same numbering and record-keeping rules, and each page explains what that document must show.
If you would rather not manage documents by hand, a TapTax account, free to start, keeps your invoices, receipts and bank transactions together and files your Making Tax Digital quarterly updates to HMRC.
Tools for this
Related guides and definitions
Frequently asked questions
What wording do I put on a reverse charge invoice?
A clear statement such as "Reverse charge: customer to account to HMRC for the VAT", with the VAT rate and amount shown but not included in the total.
Does the reverse charge apply to work for homeowners?
No. Homeowners are end users and are not VAT registered, so VAT is charged normally.
Do I still show VAT on a reverse charge invoice?
Yes. Show the rate and amount that would be charged, but leave it out of the total the customer pays you.
Invoice, get paid, stay ready for HMRC.
TapTax creates and sends your invoices, tracks which ones are paid and files your quarterly updates to HMRC. Start on the free plan, no card needed.
Get started freeSources
The rules on this page come from official guidance.