
Simplified VAT invoice
template
A shorter VAT invoice for sales of £250 or less, showing VAT-inclusive totals by rate.
Download the simplified VAT invoice template
Free, with no sign-up. Replace the words in square brackets with your own details.
Not every sale needs a full VAT invoice. For small supplies, HMRC allows a simplified VAT invoice with fewer details: your business details and VAT number, the tax point, a description, and for each VAT rate the VAT-inclusive total and the rate. It is what a till receipt from a VAT-registered shop or cafe usually is. This template sets one out for businesses that issue them by hand or by email.
- Simplified VAT invoice
- A shorter form of VAT invoice a VAT-registered business can issue when a supply is worth £250 or less including VAT. It shows the total including VAT and the VAT rate for each rate, rather than a full VAT breakdown.
When to use a simplified VAT invoice
Use a simplified VAT invoice when you are VAT registered and the supply is £250 or less including VAT. Retailers can issue one whenever the sale is £250 or less; other businesses can use one for the same amount if the customer agrees. It is ideal for small counter sales, call-outs and one-off services where a customer needs VAT evidence but a full invoice would be overkill. You cannot include exempt supplies on it, and above £250 a customer who asks must be given a full VAT invoice or a modified VAT invoice instead.
What a simplified VAT invoice must show
| What it shows | Why it matters |
|---|---|
| Your name, address and VAT registration number | Identifies you as able to charge VAT |
| The time of supply (tax point) | When the supply was made |
| A description of the goods or services | Enough to identify what was supplied |
| For each VAT rate, the total payable including VAT | The VAT-inclusive figure at that rate |
| The VAT rate for each total | So the customer can work out the VAT |
| A receipt or invoice number | Not strictly required, but makes the document easy to find again |
The customer's name and address are not required on a simplified VAT invoice, and neither is a separate VAT amount: the customer works out the VAT from the VAT-inclusive total using the VAT fraction, which is 1/6 at 20%.
An example simplified VAT invoice
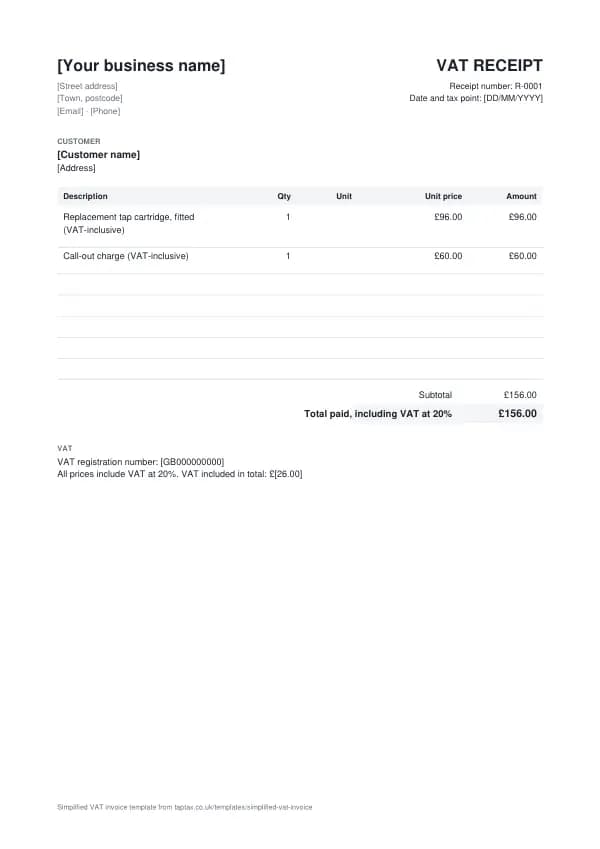
The template comes filled in with example lines like these, so you can see how each part works before replacing them with your own.
| Line | Quantity | Price | Amount |
|---|---|---|---|
| Replacement tap cartridge, fitted (VAT-inclusive) | 1 | £96.00 | £96.00 |
| Call-out charge (VAT-inclusive) | 1 | £60.00 | £60.00 |
| Subtotal | £156.00 | ||
| Total paid, including VAT at 20% | £156.00 |
Line by line: Replacement tap cartridge, fitted (VAT-inclusive), 1 × £96.00 = £96.00; Call-out charge (VAT-inclusive), 1 × £60.00 = £60.00. The subtotal is £156.00, which is also the total paid, including vat at 20% because no VAT is charged. The figures are illustrative; replace them with your own.
How to fill in the template
- Add your business name, address and VAT registration number.
- Enter the date of supply, which is the tax point for a sale paid on the spot.
- Describe each item or service and give its VAT-inclusive price.
- Show the VAT rate for each total; if everything is at 20%, say so once.
- Check the sale is £250 or less including VAT; if not, use a full VAT invoice.
- Give it to the customer and keep a copy.
Give each simplified VAT invoice its own number in a single sequence, and never reuse one. A number lets you and your customer refer to the document without confusion, and an unbroken sequence shows your records are complete. The invoice number generator suggests a format that stays tidy for years.
The £250 limit and working out the VAT
The simplified VAT invoice is only for supplies worth £250 or less including VAT. To find the VAT inside a VAT-inclusive price, multiply by the VAT fraction: 1/6 at the standard rate of 20% and 1/21 at the reduced rate of 5%. A £60 call-out charge at 20% therefore includes £10 of VAT. Card terminal slips can serve as simplified VAT invoices if you add your VAT number, the VAT rate and a description of what was sold; but if you also give an invoice or receipt, only one of the documents may be the VAT invoice. The VAT calculator works out VAT-inclusive and exclusive figures.
UK VAT rates
- Standard rate20%
- Reduced rate5%
- Zero rate0%
Simplified VAT invoice or full VAT invoice?
A full VAT invoice shows the customer's details, each line's VAT-exclusive price and the total VAT; it is required for supplies over £250 and whenever a customer asks for one. A simplified invoice is quicker and fits a till receipt, but it only works for smaller supplies. If in doubt, a full VAT invoice is always acceptable.
Retail sales and customer requests
Retailers do not have to give VAT invoices to customers who are not VAT registered, and can assume none is needed unless the customer asks. But if a VAT-registered customer asks for a VAT invoice, you must provide one, and HMRC can charge a penalty if you refuse. For sales of £250 or less, a simplified invoice satisfies the request; above that, give a full or modified VAT invoice.
Mixed rates on one receipt
A cafe selling a zero-rated cold sandwich and a standard-rated hot drink, or a shop selling food and household goods, can show both on one simplified invoice, as long as the VAT-inclusive total and the rate are shown for each rate. Many till systems do this with a code next to each item and a summary at the bottom. Exempt supplies must not be included on a simplified invoice at all.
Keeping your copies
Simplified invoices are part of your VAT records. If you use a till, keep the daily Z-reading and the till roll or its electronic equivalent; if you issue them by hand, keep a copy of each. Under Making Tax Digital for VAT, your sales must be recorded digitally, even if the receipt itself was on paper.
An example, worked through
A plumber replaces a tap cartridge for £96 and charges a £60 call-out, both including VAT at 20%, total £156. The simplified invoice shows the plumber's name, address and VAT number, the date of the visit, a description of each item with its VAT-inclusive price, and a note that all prices include VAT at 20%. The customer's bookkeeper works out the VAT as one sixth of £156, which is £26.00, and the net cost as £130.00. Stating the VAT amount on the receipt is not required, but it saves the customer the sum and reduces queries.
Common simplified VAT invoice mistakes
- Using it for sales over £250. Above the limit a customer who asks must get a full or modified VAT invoice.
- Leaving off the VAT number. Without it the document is not a VAT invoice and the customer cannot reclaim.
- Including exempt items. Exempt supplies cannot go on a simplified VAT invoice.
Checklist before you send it
Before a simplified VAT invoice goes out, check it against the list of what it must show:
- Your name, address and VAT registration number is on it and correct.
- The time of supply (tax point) is on it and correct.
- A description of the goods or services is on it and correct.
- For each VAT rate, the total payable including VAT is on it and correct.
- The VAT rate for each total is on it and correct.
- A receipt or invoice number is on it and correct.
- A copy is saved with your records.
Sending it
Send the simplified VAT invoice as a PDF attached to an email, not as an editable file. In the email, say what it is, its number, the amount and any date that matters, so the reader can act without opening the attachment. Send it to the person or inbox that deals with it, which for a business is often an accounts address rather than the person you worked with, and keep a copy of the email and the PDF together in your records.
Keep a copy
You must keep your records for at least 5 years after the 31 January submission deadline of the relevant tax year.
Keep a copy of every simplified VAT invoice you issue or receive, digital is fine, with the payments that relate to it. From 6 April 2026, sole traders and landlords with qualifying income over £50,000 must keep digital records and send HMRC quarterly updates under Making Tax Digital, falling to £30,000 from April 2027 and £20,000 from April 2028. The MTD requirement checker shows when it applies to you, and how long to keep invoices covers retention.
Download the simplified VAT invoice template
The template comes as a Word document for Word, Google Docs and Pages, an Excel workbook for Excel and Google Sheets, and a print-ready PDF. Replace the words in square brackets with your own details. In the Excel version each line, the subtotal and the total are formulas, so the figures update as you type.
Related documents in the same family: the zero-rated invoice template, VAT-exempt invoice template, flat rate scheme invoice template, reverse charge invoice template and VAT invoice template. All of them follow the same numbering and record-keeping rules, and each page explains what that document must show.
A TapTax account, free to start, creates and sends invoices, tracks which are paid, keeps receipts and bills with your records, and files your quarterly updates to HMRC from the same data.
Tools for this
Related guides and definitions
Frequently asked questions
What is a simplified VAT invoice?
A shorter VAT invoice for supplies of £250 or less including VAT, showing your VAT details, the date, a description, and the VAT-inclusive total and rate for each VAT rate.
Does a simplified invoice need the customer's name?
No. It needs your name, address and VAT number, the tax point, a description and the VAT-inclusive totals and rates.
Can a card receipt be a VAT invoice?
Yes, if you add your VAT number, the VAT rate and a description of what was sold, for sales of £250 or less.
Invoice, get paid, stay ready for HMRC.
TapTax creates and sends your invoices, tracks which ones are paid and files your quarterly updates to HMRC. Start on the free plan, no card needed.
Get started freeSources
The rules on this page come from official guidance.