
Export invoice
template
An invoice for sales to overseas customers, with the right VAT treatment for goods and services.
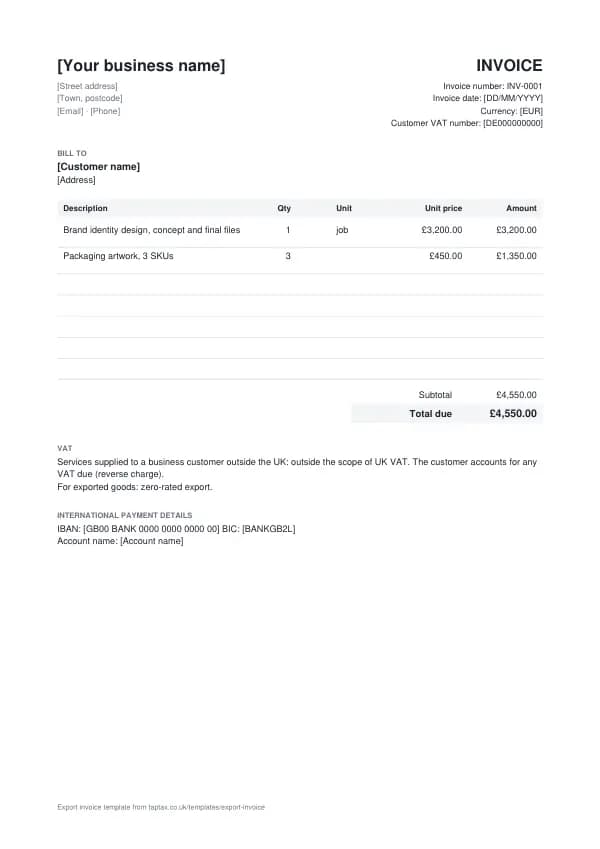
Download the export invoice template
Free, with no sign-up. Replace the words in square brackets with your own details.
Selling abroad changes the VAT on your invoice, and the rules differ for goods and services. Exported goods are zero-rated if you keep proof they left the UK. Services to overseas business customers are usually outside the scope of UK VAT, with the customer accounting for any VAT in their own country. This template has a line for each case, so the invoice says why no UK VAT has been charged.
- Export invoice
- An invoice for a sale to a customer outside the UK. For goods, it records a zero-rated export; for services, it records a supply that is usually outside the scope of UK VAT when the customer is an overseas business.
When to use a export invoice
Use an export invoice when your customer is outside the UK: a German company buying design work, an American client paying for consultancy, or an Irish shop buying your products. For physical goods going through customs, pair it with a commercial invoice, or combine the two. For services, the key question is whether the customer is a business or a consumer and where they belong, because that decides where the service is taxed. Services to overseas consumers can still carry UK VAT, depending on the service.
What a export invoice must show
| What it shows | Why it matters |
|---|---|
| Your name, address and VAT number if registered | Who is supplying |
| The customer's name, full address and country | Shows the customer belongs outside the UK |
| The customer's VAT or business registration number, for services to businesses | Evidence they are in business |
| Invoice number, date and currency | Identifies the sale |
| A description of the goods or services with prices | What is being sold |
| The VAT treatment: zero-rated export, or outside the scope of UK VAT | Explains why no UK VAT is charged |
| Payment details for international transfers (IBAN and BIC) | How overseas customers pay you |
An example export invoice
The template comes filled in with example lines like these, so you can see how each part works before replacing them with your own.
| Line | Quantity | Price | Amount |
|---|---|---|---|
| Brand identity design, concept and final files | 1 job | £3,200.00 | £3,200.00 |
| Packaging artwork, 3 SKUs | 3 | £450.00 | £1,350.00 |
| Subtotal | £4,550.00 | ||
| Total due | £4,550.00 |
Line by line: Brand identity design, concept and final files, 1 job × £3,200.00 = £3,200.00; Packaging artwork, 3 SKUs, 3 × £450.00 = £1,350.00. The subtotal is £4,550.00, which is also the total due because no VAT is charged. The figures are illustrative; replace them with your own.
How to fill in the template
- Add your details and the customer's full address and country.
- For services to a business, add their VAT or business registration number.
- Choose the currency and list the goods or services with prices.
- Add the VAT note: zero-rated export for goods, or outside the scope for business services.
- Add IBAN and BIC so the customer can pay internationally.
- Keep evidence of export or of the customer's business status with the invoice.
Give each export invoice its own number in a single sequence, and never reuse one. A number lets you and your customer refer to the document without confusion, and an unbroken sequence shows your records are complete. The invoice number generator suggests a format that stays tidy for years.
Where services are taxed
For most services supplied to a business customer, the place of supply is where the customer belongs. If that is outside the UK, the supply is outside the scope of UK VAT, and the customer accounts for any local VAT under their own reverse charge. For services to consumers, the general rule is that the place of supply is where the supplier belongs, so UK VAT is charged, but there are important exceptions, such as land-related services, events, and some services to consumers outside the UK and EU. Electronically supplied services to EU consumers are taxed where the consumer lives. VAT Notice 741A sets out the rules and exceptions.
UK VAT rates
- Standard rate20%
- Reduced rate5%
- Zero rate0%
Export invoice or commercial invoice?
An export invoice is your sales invoice and records the VAT treatment. A commercial invoice is the customs document that travels with goods. For services, only the export invoice is needed. For goods, many businesses use one document with both sets of details.
Evidence of business status
To treat a service as supplied to an overseas business, you need reasonable evidence that the customer is in business. For EU customers, the VAT number is the usual evidence, and you can check it on the EU's VIES service. For customers elsewhere, a business registration number, a company website or letterhead, and correspondence showing the business relationship all help. Keep that evidence with the invoice, because if HMRC decides the customer was a consumer, UK VAT might have been due.
Invoicing in foreign currencies
You can invoice in the customer's currency, but your records and any VAT return are in sterling. Record the sterling value at a consistent exchange rate, such as HMRC's published monthly rates or the rate on the day. When the payment arrives at a different rate, the difference is a gain or loss for Income Tax, not for VAT. Payment platforms that hold foreign currency balances can save on conversion fees if you have regular overseas customers.
VAT registration and overseas sales
Services supplied to overseas businesses that are outside the scope of UK VAT do not count towards the £90,000 VAT registration threshold. Zero-rated exports of goods do count, because they are taxable supplies. So a designer with mostly overseas business clients may stay below the threshold on UK turnover alone, while a maker exporting goods counts every sale. If you are registered, both still go on your VAT return: exports of goods in box 6, and services outside the scope in box 6 as well.
Getting paid from abroad
Give your IBAN and BIC (SWIFT code) for international bank transfers, and say who pays the charges, as intermediary banks can take a cut. Payment platforms, multi-currency accounts and card links are often cheaper and faster for small invoices. Set payment terms in writing, since chasing an unpaid invoice abroad is harder and the UK's late payment legislation may not apply to contracts under foreign law. Consider asking new overseas customers for a deposit.
Overseas tax registration
Selling to consumers in some countries can require you to register for their VAT or sales tax, for example digital services to EU consumers, or goods sold to consumers above a country's threshold. The EU's One Stop Shop schemes let you account for EU VAT through one registration. Check the rules for any country where you sell regularly to consumers, before rather than after your sales there grow.
Common export invoice mistakes
- Charging UK VAT on services to overseas businesses. Most are outside the scope of UK VAT, with the customer accounting for VAT locally.
- No evidence the customer is a business. Keep their VAT or registration number and correspondence.
- Zero-rating goods without proof of export. Keep shipping evidence, or UK VAT is due.
Checklist before you send it
Before a export invoice goes out, check it against the list of what it must show:
- Your name, address and VAT number if registered is on it and correct.
- The customer's name, full address and country is on it and correct.
- The customer's VAT or business registration number, for services to businesses is on it and correct.
- Invoice number, date and currency is on it and correct.
- A description of the goods or services with prices is on it and correct.
- The VAT treatment: zero-rated export, or outside the scope of UK VAT is on it and correct.
- Payment details for international transfers (IBAN and BIC) is on it and correct.
- A copy is saved with your records.
Sending it
Send the export invoice as a PDF attached to an email, not as an editable file. In the email, say what it is, its number, the amount and any date that matters, so the reader can act without opening the attachment. Send it to the person or inbox that deals with it, which for a business is often an accounts address rather than the person you worked with, and keep a copy of the email and the PDF together in your records.
Keep a copy
You must keep your records for at least 5 years after the 31 January submission deadline of the relevant tax year.
Keep a copy of every export invoice you issue or receive, digital is fine, with the payments that relate to it. From 6 April 2026, sole traders and landlords with qualifying income over £50,000 must keep digital records and send HMRC quarterly updates under Making Tax Digital, falling to £30,000 from April 2027 and £20,000 from April 2028. The MTD requirement checker shows when it applies to you, and how long to keep invoices covers retention.
Download the export invoice template
The template comes as a Word document for Word, Google Docs and Pages, an Excel workbook for Excel and Google Sheets, and a print-ready PDF. Replace the words in square brackets with your own details. In the Excel version each line, the subtotal and the total are formulas, so the figures update as you type.
Related documents in the same family: the invoice template, self-billing invoice template, pro forma invoice template, commercial invoice template and e-invoice template. All of them follow the same numbering and record-keeping rules, and each page explains what that document must show.
A TapTax account, free to start, creates and sends invoices, tracks which are paid, keeps receipts and bills with your records, and files your quarterly updates to HMRC from the same data.
Tools for this
Related guides and definitions
Frequently asked questions
Do I charge VAT to overseas customers?
For exported goods, usually not: they are zero-rated with proof of export. For services to overseas businesses, usually not: they are outside the scope of UK VAT. Services to consumers can differ.
What wording goes on an invoice to an overseas business?
A note that the services are outside the scope of UK VAT and the customer accounts for any VAT due, or that goods are a zero-rated export.
Do overseas sales count towards the VAT threshold?
Zero-rated exports of goods do. Services outside the scope of UK VAT do not.
Invoice, get paid, stay ready for HMRC.
TapTax creates and sends your invoices, tracks which ones are paid and files your quarterly updates to HMRC. Start on the free plan, no card needed.
Get started freeSources
The rules on this page come from official guidance.